

YNAB
by ynab.com
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
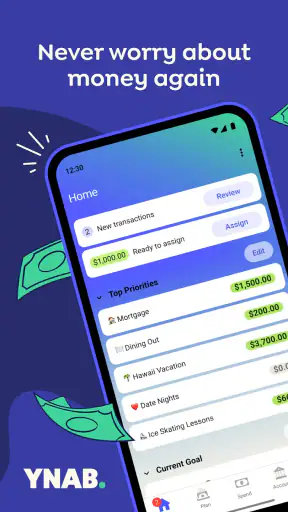
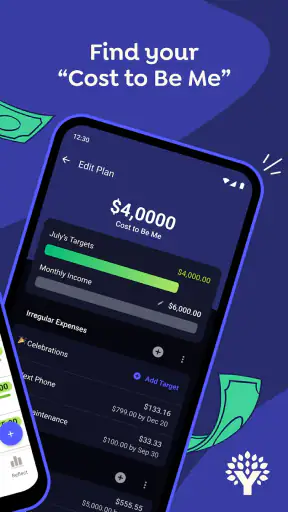
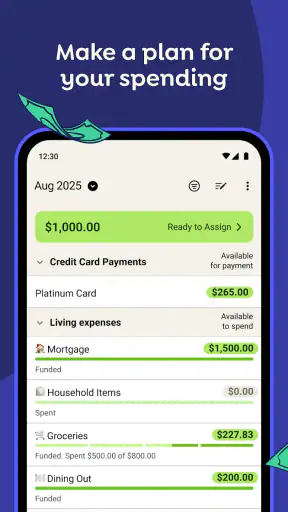
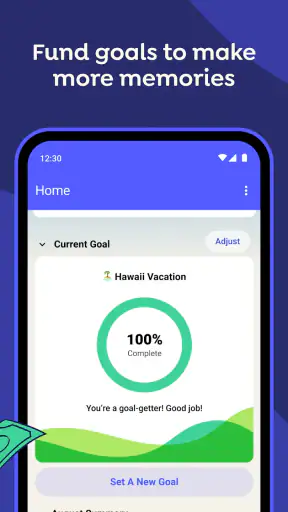
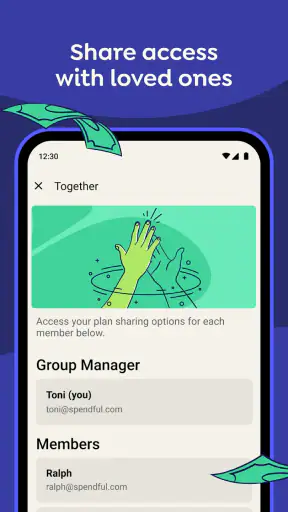
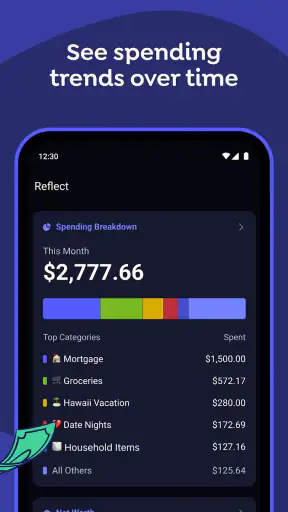
 Analysis by Getfullapps
I started using YNAB because household budgeting is rarely just about arithmetic. It is about deciding which bills get attention first, making room for irregular expenses, and avoiding the awkward moment when two people assume the other has already handled something. YNAB approaches that problem as a hands-on finance app rather than a passive account viewer. In my experience, its strongest idea is simple: give every incoming dollar a job before it disappears into everyday spending.
That makes it especially interesting for couples, roommates, and families who need a shared view of priorities without turning every purchase into an argument. It is a finance app from ynab.com, available free to install with in-app purchases ranging from $14.99 to $109.00 per item. The app is rated for Everyone, so its presentation is approachable, although the budgeting decisions it encourages are most useful when an adult takes responsibility for the plan.
How YNAB works when more than one person uses the household budget
A realistic example is a couple managing one household while each person makes separate daily purchases. One person pays the electricity bill, the other buys groceries, and both occasionally spend from the same general pool. Without a shared plan, the balance in a bank account can look healthy even when rent, annual insurance, school costs, or a car repair are already waiting in the background.
YNAB helps me think about that money by purpose instead of by account balance. I can create categories for obligations, near-term spending, and less frequent costs, then assign available money according to what matters first. That shift is more useful than simply checking whether the bank balance has gone up or down. A balance tells me what exists; the budget asks what that money must do next.
For shared use, the key benefit is a common language. “We have money” becomes less vague when it means the grocery category is funded, the rent category is protected, and the next service bill has already been considered. This reduces the need to remember every financial detail mentally. It also makes a conversation more practical: instead of blaming someone for spending, we can look at which category needs adjusting.
The app is not magic, though. It works best when everyone who spends from the household understands the basic routine. A person who records purchases carefully while another person ignores the plan can create confusion quickly. YNAB can organize decisions, but it cannot make two people agree about priorities or remember a purchase that nobody enters.
Building a budget around real household timing
The first useful habit is to budget according to when money is available, not according to an ideal monthly template. If income arrives at different times, I would start with the bills and spending that must be covered before the next income arrives. That makes the plan more realistic than assigning money that has not yet reached the household.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Irregular expenses deserve special attention. A yearly renewal, seasonal clothing, gifts, or maintenance can feel like a surprise only because the budget treated it as invisible. I find it more effective to create a category early and add to it gradually. When the expense finally appears, the money is already waiting instead of competing with groceries or utilities.
A less obvious advantage is that this method exposes trade-offs early. If there is not enough available money to fund every category, the app forces a decision about what matters most right now. That can feel uncomfortable, but it is healthier than pretending every goal is equally funded. In a household, that visibility is often more valuable than a polished chart.
Setup boundaries matter more than the first budget
Before inviting another person into a household routine, I would agree on what the budget is meant to cover. Is it only shared bills? Does it include groceries and transport? Are personal purchases kept separate? These boundaries are not minor details. They determine whether the categories feel fair or whether the budget starts monitoring spending that should remain private.
YNAB is easier to use when the category structure reflects the household’s actual agreements. I would avoid creating an enormous list of tiny categories at the beginning. Too much detail makes every purchase feel like administrative work. A smaller set of meaningful categories is usually easier to maintain, especially for someone who is joining the system after the budget has already been built.
At the same time, overly broad categories can hide problems. Combining all household costs into one “bills” category may look tidy, but it does not show whether a large annual payment is being prepared for. My preferred compromise is to separate expenses when their timing or importance is different, not merely because the app allows more labels.
One practical setup rule is to decide who handles corrections. If a transaction is entered incorrectly, someone should know whether to fix the category, move money between categories, or wait until both people review the plan. This avoids silent changes that make the budget technically accurate but socially confusing.
Coordination without turning budgeting into surveillance
Shared finances need coordination, but coordination is not the same as watching every purchase. I would use YNAB to make shared commitments visible, while keeping personal boundaries clear. For example, a household can agree on the grocery amount and the bill schedule without requiring both people to justify every small personal expense.
The most useful routine I found is a short review after a group of purchases rather than a long financial meeting at the end of the month. Entering or checking transactions while they are still familiar makes mistakes easier to correct. It also lets the household notice a category running low before the problem becomes urgent.
When one person spends from a shared category, the important question is not who spent the money but whether the category still matches the plan. If groceries cost more than expected, the household can choose where the difference comes from. That is a concrete decision. It is much better than discovering later that the account balance is lower and nobody knows why.
A useful advanced workflow is to treat category changes as conversations about priorities. Moving money from entertainment to a medical expense, for instance, is not a failure of the budget. It is the budget recording a new reality. I would rather make that adjustment openly than keep an outdated plan simply because it looked neat at the start of the month.
Another trade-off is convenience. Some people want a finance app that automatically summarizes accounts with almost no input. YNAB asks for more active participation. That extra effort is the source of much of its clarity, but it is also the reason a household that dislikes manual review may lose interest. If nobody wants to maintain categories, a simpler tracking app may be a better fit.
Account boundaries and shared-device expectations
Using a finance app on a shared phone or tablet requires common-sense boundaries. I would avoid assuming that everyone using the device should see every part of the household’s financial picture. Before setting up access, decide which information is genuinely shared and which belongs to one person. The app can support a household plan, but the people involved still need to define their own privacy expectations.
This is particularly important in homes where a child occasionally uses the same device. The Everyone age rating makes the app’s general classification broad, but that does not mean a child should be responsible for household financial decisions. I would treat younger users as learners who can discuss categories and goals with an adult, not as independent managers of bills or account information.
For teenagers, YNAB could be useful as a teaching environment if an adult explains the reasoning behind categories rather than simply demanding that every purchase be recorded. A young person can learn that money reserved for a future need is not spare cash. However, the adult should decide what information is appropriate to share and should review the plan before any important financial change.
Trust also matters between adults. A shared budget should not become a hidden scoring system for who is “better” with money. I found the app more helpful when categories were treated as agreements and signals, not as evidence in an argument. If one person repeatedly refuses to participate, the problem is probably the household arrangement rather than the software.
What the app does well compared with simpler alternatives
Many ordinary banking apps are excellent for checking balances and recent transactions, but they usually leave the user to interpret what the money is for. Spreadsheet budgets offer flexibility, yet they require more manual design and maintenance. Basic expense trackers can show where money went after the fact, but they may not encourage a decision about what available money should cover next.
YNAB’s difference is its forward-looking, category-based workflow. It makes me decide how current money should be allocated, then gives me a structure for adjusting that plan when life changes. That is more demanding than opening a banking app, but it can be more useful for households living with uneven expenses or competing priorities.
The trade-off is that this approach may feel excessive for someone who only wants a monthly spending summary. If your finances are very simple, your income and expenses are predictable, and you already save consistently, YNAB may add a layer of planning you do not need. Likewise, a person who wants investment research, lending tools, or a full financial dashboard should look for an app designed around those functions rather than expecting this budgeting system to cover everything.
I also would not choose it for a household that refuses to discuss money. No budgeting tool can resolve disagreements about debt, discretionary spending, or unequal contributions. YNAB can make the numbers easier to see, but visibility sometimes reveals a conversation that was already overdue.
Everyday friction I noticed during use
The main friction is consistency. A budget can look perfectly organized while still being wrong if purchases are missing or placed in the wrong categories. The solution is not to wait for a dramatic monthly cleanup. I would build a small checking habit into the day or week, depending on how often the household spends.
Another challenge is emotional: giving every dollar a job can make spending feel restrictive at first. A category with money in it feels available, while an empty category forces a choice. I eventually found that this tension was useful, but only after allowing realistic amounts for fun and flexible spending. A budget that leaves no room for ordinary enjoyment is unlikely to survive.
New users may also need time to understand the difference between moving money and earning more money. Reassigning funds does not solve an income problem; it changes which goal receives attention. That distinction becomes important when a household repeatedly borrows from future categories to cover current costs. The app can reveal the pattern, but the remedy may require reducing expenses or changing income, not rearranging labels.
For shared use, I recommend starting with one complete pay cycle rather than trying to model every possible future expense immediately. Fund essential categories, add one or two irregular obligations, and observe where the plan breaks. Those mistakes teach more than a complicated setup built on guesses.
Who should use it and who should skip it
I would recommend YNAB to someone who wants an active budgeting system, especially if money feels scattered across bills, goals, and everyday spending. It is a strong match for couples who need a shared plan, roommates dividing household costs, and people whose irregular expenses regularly catch them off guard.
It is also suitable for a person willing to learn a method rather than merely install an app. The free price shown for the app makes trying it straightforward, but the in-app purchases mean that continued use can involve a paid option. I would review the purchase terms carefully before committing, particularly if several people are deciding together whether it fits the household.
I would skip it if you want completely passive tracking, dislike assigning categories, or expect the app to make financial decisions automatically. I would also choose another tool if your main need is detailed investing, tax preparation, credit monitoring, or a shared bill-splitting service. YNAB is focused on giving available money a purpose, and that focus is both its strength and its boundary.
Device compatibility, maturity, and practical expectations
The current version is 26.32.0 and requires at least OS 11, so I would check the operating system of an older phone or tablet before planning a shared setup. That is especially relevant in households where one person uses a spare device as the budget screen. Compatibility is a small detail, but it can become a real obstacle when the least-used household device is also the one everyone expects to access.
YNAB has been available since October 20, 2015, and its scale suggests that it is not a niche experiment: it has more than a million installs, an average rating of 4.6, and roughly twenty-five thousand ratings. Those figures do not guarantee that every household will enjoy the method, but they do make it easier to find a large community of people familiar with the style of budgeting.
The Everyone rating is reassuring for general accessibility, though I would still keep adult oversight around real financial accounts and household decisions. Age suitability and financial responsibility are different questions. A child may understand a category, while an adult remains responsible for deciding what the household can safely spend.
My household verdict
After using YNAB as a budgeting tool rather than a simple expense diary, I see its biggest value in coordination. It gives a household a place to turn vague intentions into visible priorities: this money is for the bill, that money is for groceries, and another amount is being protected for an expense that has not happened yet.
The real benefit is not seeing every transaction; it is making the next decision before the money disappears. That requires participation, honest categories, and agreed boundaries. For a couple or household prepared to do that work, the app can make money conversations calmer and more specific.
My recommendation is conditional but positive. Try it if you want a deliberate, category-driven system and are willing to maintain it together. Start small, decide what belongs in the shared plan, and leave reasonable room for personal spending. If your household wants effortless summaries or refuses shared financial routines, choose a lighter alternative instead. YNAB is most convincing when people use it as a common planning language, not when they expect it to replace communication.
Pros
- Clear budgeting system helps users give every dollar a specific job.
- Bank syncing can reduce manual entry for supported financial institutions.
- Detailed reports make spending habits and progress easy to review.
- Shared plans support household budgeting with synchronized information.
- Strong educational resources help beginners build better money habits.
Cons
- The subscription cost may be difficult to justify for simple budgeting needs.
- Bank connections can occasionally require reauthorization or manual fixes.
- The learning curve may feel steep for users new to envelope budgeting.
- Some features depend on regional bank and currency support.
- Entering cash transactions consistently requires ongoing user discipline.
FAQs for YNAB
What is YNAB, and how does it help with budgeting?
YNAB, short for You Need A Budget, is a personal finance app designed around giving every dollar a specific job. After entering your income, bills, savings goals, and everyday expenses, you assign available money to categories before spending it. This approach helps you understand what you can afford, prepare for upcoming costs, and make more deliberate financial decisions instead of simply tracking transactions after they happen.
Is YNAB free to download and use?
YNAB can usually be downloaded for free, but continued access to its full budgeting tools requires a paid subscription after the trial period. The subscription includes features such as synchronization across devices, bank connectivity where supported, goal tracking, reports, and access through the web, Android, and iOS apps. Pricing and trial availability may vary by region, so check the current terms before subscribing.
Can YNAB connect to my bank accounts?
YNAB supports direct or partner-based bank connections for many financial institutions, allowing transactions to be imported and reviewed inside the budget. Availability depends on your country, bank, and account type, and some connections may occasionally need to be repaired. You can also add transactions manually or import them using supported methods, which is useful when automatic connectivity is unavailable or you prefer greater control.
Is YNAB suitable for beginners who have never used a budgeting app?
YNAB can be suitable for beginners, although its method may feel different from a simple expense tracker. The app expects you to plan with the money currently available and assign it to categories such as rent, groceries, debt payments, and savings. Its explanations, onboarding guidance, and educational resources make the system easier to learn, but consistent updates and active participation are important for the best results.
Is my financial information safe when using YNAB?
YNAB uses security measures intended to protect account and budgeting information, including encrypted connections and authentication controls. However, no online service can eliminate every security risk. Before connecting accounts, review YNAB’s current privacy policy and security information, use a strong unique password, enable available multi-factor authentication, and avoid accessing your budget from untrusted devices or public networks whenever possible.

YNAB
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@ynab.com, visit https://www.ynab.com, or review their https://www.youneedabudget.com/privacy-policy/.










